


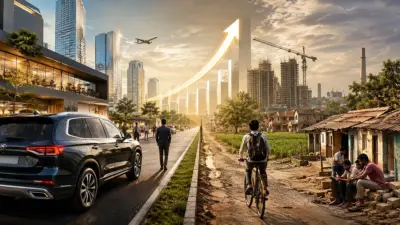
In 2015, SUVs' accounted for roughly a fifth of the cars India bought. By 2025, they accounted for more than half, while the entry-level hatchback, for decades the vehicle which carried an Indian family into the middle class, has seen its market roughly halve.
Data from the Society of Indian Automobile Manufacturers and the Federation of Automobile Dealers Associations tell the story plainly enough. India is buying more cars. It is also buying rather different cars.
This shift is visible well-beyond the showroom. There are more people travelling by air, wider access to digital payments and financial services, and a readiness to spend on products and experiences, same a generation ago would have counted as luxuries. Premium consumption has consistently outpaced the mass market. This is more than a change in taste, it is a useful indication of where purchasing power is accumulating and it raises the question the aggregate growth figures tend to obscure: how widely is this growth being transmitted?
The household balance sheet points the same way. Reserve Bank of India data show net household financial savings recovering to about 7% of gross national disposable income in FY25, after the multi-decade lows of the preceding years - an improvement, but one driven as much by households paying down debt as by any surge in saving, and still modest set against the pace of the wider economy. At the same time, corporate profits have reached seventeen-year highs on the Nifty-500 and government capital expenditure has risen substantially. The result is an unusual combination: the state is investing, affluent households are spending and corporate margins are strong, while the financial position of the broader household sector is considerably less comfortable.
None of this diminishes the scale of India's progress. Living standards have unquestionably improved. Poverty has fallen substantially, while access to electricity, cooking gas, banking, and food support has expanded across hundreds of millions of households. The more difficult question is what happens after basic needs are met. Does the same economy create enough productive employment and rising incomes to allow a much larger share of households to participate in discretionary consumption and build financial security?
FM Sitharaman lands in US for six-day visit for G20 talks and meeting with business leadersAnirudh Krishna's The Broken Ladder offers a useful perspective where he describes the coexistence of India's globally connected "dollar economy" with a much larger "rupee economy", where incomes and opportunities remain far more constrained. His broader argument is economic growth does not automatically translate into upward mobility when access to education, information, networks, and suitable employment remains uneven.
And there is an important economic consequence. A highway can be built through public investment, but it is the factories, businesses and jobs which turn infrastructure into sustained private demand require something more: companies must believe households will have the incomes to buy what they produce. Public capital can lay the ground for growth; it cannot by itself supply the demand that makes private investment worthwhile.
India's experience with manufacturing illustrates the gap. The sector's share of output has barely shifted for decades, at around 13% of GDP on World Bank estimates, even as Vietnam and Bangladesh have used labour-intensive manufacturing to build far larger employment engines, the kind which can pull millions of workers from low-productivity agriculture into steady wages. India has grown, in other words, without the employment intensity, historically, converted growth into broad-based income gains.
This helps explain why strong aggregate growth can coexist with very different experiences across households and businesses. The dollar economy and the rupee economy are not separate countries; they are the same economy, producing booming premium consumption and record corporate profits at one end while, at the other, a graduate cycles through months of job applications and a small business struggles to find the demand that would justify expanding. What looks like a single growth story from the aggregate data is, on the ground, at least two. Unemployment among graduates runs at more than three times the national rate, even as youth joblessness has begun to ease.
Consumption, however, can be transient. A household may bring forward a purchase, borrow to finance it, or trade up when sentiment is strong. Rising median incomes are different. When more households have steadily increasing incomes, consumption becomes less dependent on credit or confidence, savings can deepen and businesses can invest against a more dependable base of demand. This turns consumption from a cyclical boost into a durable growth cycle.
The next phase therefore matters more than the last. If public investment and affluent consumption can broaden into rising household incomes, stronger small businesses, higher savings and eventually a revival in private investment, India's growth will acquire a much wider base. The opportunity would no longer be concentrated in the parts of the economy already benefiting from government spending or premium consumers.
India is growing. The next question is how broadly can growth spread.